- News
- News Desk
- Source: European Central Bank https://www.ecb.europa.eu//press/key/date/2026/html/ecb.sp261005~1d8d998ef4.en.html
The European Central Bank faces significant diagnostic challenges in determining the right monetary policy stance, Executive Board member Philip R. Lane said in a keynote speech at the ECB Conference on Monetary Policy 2026 in Frankfurt am Main on 5 October 2026, pointing to the need to distil the medium-term inflation outlook from multiple shocks, with headline inflation at 3.8 per cent in September.
Key facts
What are the main diagnostic challenges?
- Philip R. Lane, a member of the ECB's Executive Board, spoke at the ECB Conference on Monetary Policy 2026 in Frankfurt am Main on 5 October 2026.
- The ECB's interest rate decisions rest on three criteria: the inflation outlook and its risks, underlying inflation dynamics, and the strength of monetary policy transmission.
- September inflation data show headline inflation at 3.8 per cent, with energy inflation at 18.8 per cent.
- The ECB has published scenarios examining different paths for the energy supply shock, which Lane said have helped guide understanding of the shock's macroeconomic impact.
Lane said the primary diagnostic task is to isolate the medium-term component of inflation when multiple shocks hit the economy over different horizons. The ECB's medium-term outlook is based on an integrated assessment of all relevant factors, a process that is highly data-dependent but neither reliant on a single data point nor on a mono-causal narrative, he added.
Although the energy supply shock is currently the main driver of inflation, Lane said the ECB's assessment of the medium-term outlook considers a wide range of factors. These include the magnitude and likely duration of the energy shock, the scale and persistence of pass-through from energy to non-energy inflation, and other factors such as fiscal policy, artificial intelligence and financial conditions that both intermediate the shock's transmission and have direct implications for medium-term inflation. How does the ECB assess inflation risks?
According to Lane, the ECB's monetary policy statement contains a substantial risk assessment section listing the main risks flagged by the Governing Council. The potential macroeconomic impact of each risk factor is rigorously modelled by Eurosystem staff, and in some cases the ECB publishes scenarios showing how inflation and activity might respond to specific risk events.
This year, the ECB has published scenarios examining different paths for the energy supply shock, which Lane said have been helpful in guiding understanding of how the ECB assesses the macroeconomic impact of alternative energy price paths. However, he noted that published scenarios tend to focus on single risk factors, whereas monetary policy decisions take into account a broad range of scenarios and sensitivity analyses beyond those most recently published.
Lane also stressed that each energy supply shock scenario contains ancillary assumptions about the speed and intensity of pass-through to non-energy inflation and the impact on financial conditions and activity levels. These assumptions need to be compared over time with accumulating evidence on these mechanisms. What role does underlying inflation play?
On the second criterion, underlying inflation, Lane said that as time passes since the origin of the energy shock, it becomes increasingly valuable to examine realised values of underlying inflation indicators. This is especially useful given the wide error bands around medium-term forecasts in times of high uncertainty. No single indicator provides sufficient guidance, he added, as the ECB maintains a battery of underlying inflation measures.
Because the strength and persistence of pass-through from an energy shock to non-energy inflation is highly context-specific and depends on a range of covariates, Lane said learning from the evolution of underlying inflation provides important discipline in the conduct of monetary policy. How strong is monetary transmission?
The third criterion is the strength of monetary transmission. Lane explained that overall financial conditions play a dual role: for any given policy rate, a tightening in broader financial conditions, such as higher long-term bond yields, directly reduces activity and inflation; and financial conditions are a primary factor in determining the strength of monetary transmission and thus the appropriate policy stance for a given inflation outlook.
As time passes since the energy shock, Lane said it is also increasingly relevant to study the impact of policy rate decisions taken in response to the shock. The ECB closely tracks measures of financial conditions and financing conditions, including the ECB Macro-Finance Financial Conditions Index and the ECB-BIG index, which provides a timely, integrated assessment of intermediation conditions across banks and non-bank financial intermediaries.
Looking ahead, Lane's remarks suggest the ECB will continue to rely on a broad set of indicators and scenarios to navigate the uncertain inflation environment, with the next inflation data and the Governing Council's forthcoming policy meetings likely to provide further signals on the appropriate stance. The ECB's next monetary policy meeting is scheduled for 29 October 2026, when the Governing Council will reassess the inflation outlook and transmission conditions.
Source: European Central Bank
 — Euro area firms reported a further net tightening of bank loan conditions in the third quarter of 2026, with a net 46% facing higher interest rates and a wideni
 — European Commission President Ursula von der Leyen told Hungary's National Assembly in Budapest that EU funding is back and reform conditions are being met, as
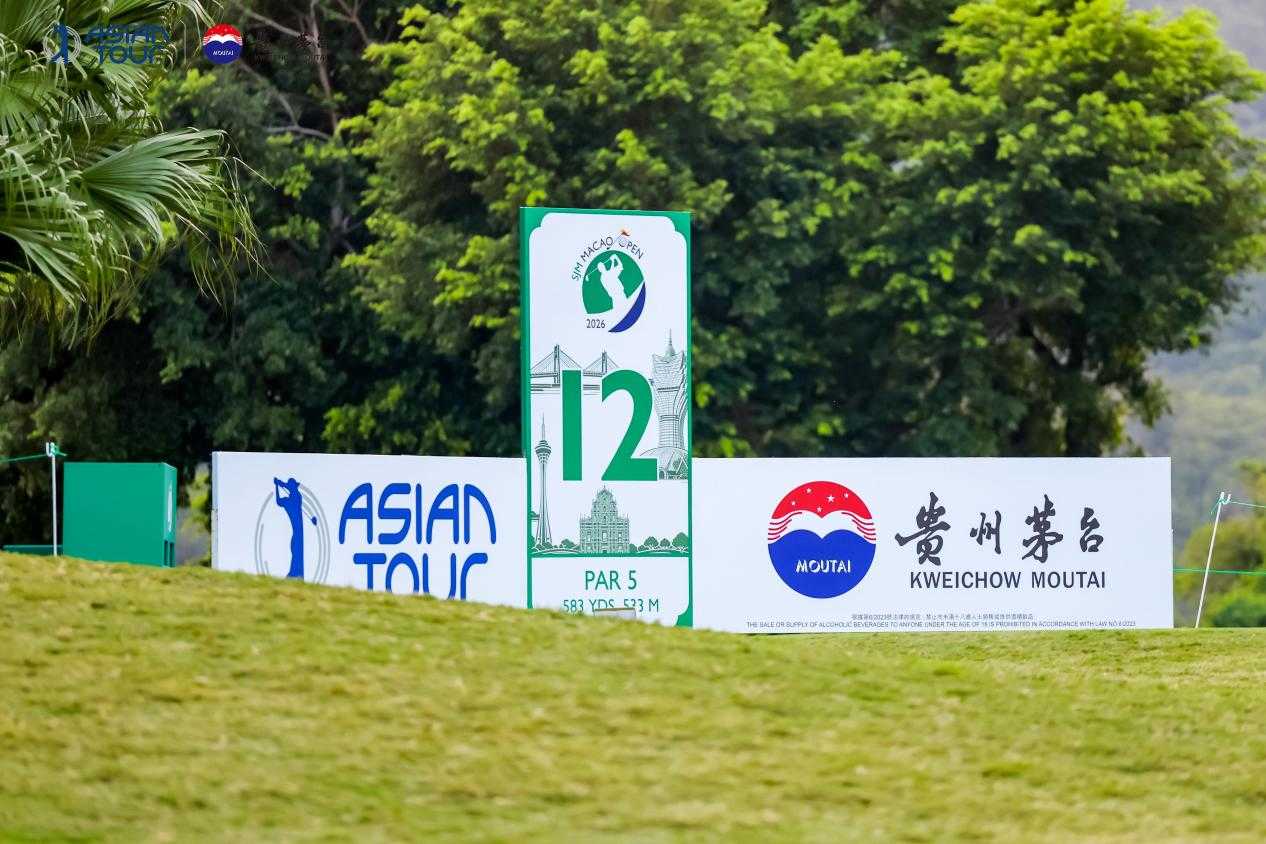 — The four-day Macao Open 2026 concluded on 18 Octoberat the Macau Golf & Country Club. After four rounds of intense competition, Chinese Taipei’s Wang Wei-Hsuan